
In my post Mr. Gorbachev, Rebuild This Wall! I talked about the problem in Europe of far too many groups of takers and not a large enough pool of contributors. They are in good company when it comes to a skewed taker/contributor ratio with the good ol’ U.S. of A.
The most obvious place to look is Social Security. Social Security is something I never used to think about much, it was to me just a sinkhole where part of my wages disappeared to that I assumed I would never get a penny back from. Now that I am in my 50s, while I am still over a decade away from being eligible it is something to think about.
Social Security has rightly been compared to a Ponzi scheme as current workers pay for the benefits of current beneficiaries. This is in sharp contrast to how most people understand Social Security which is more akin to a 401k or a savings account, as if they have an account that is their money. It is not.
Like most people I have paid an enormous amount into Social Security that I would frankly prefer to have had available to invest on my own, and if I had I would be retired more or less already. A system, even one administered by the government, that automatically deducted a percentage of pay matched by your employer and then invested those funds conservatively would be better and more sustainable than one that is based on today’s workers paying for the retirement income of yesterday’s workers. Better yet would be a privately operated system that leaves the responsibility for retirement planning solely on the person who will some day retire.
What is the unspoken but very real problem with that model, and I say this as someone who worked in the retirement plan business for a lot of years, is that leaving it up to most workers to save for their retirement means the vast majority of people would hit retirement age with no savings at all. That is a conversation for a different day but the reality is that the Social Security system is in big trouble because the ratio of contributors to beneficiaries keeps shrinking….
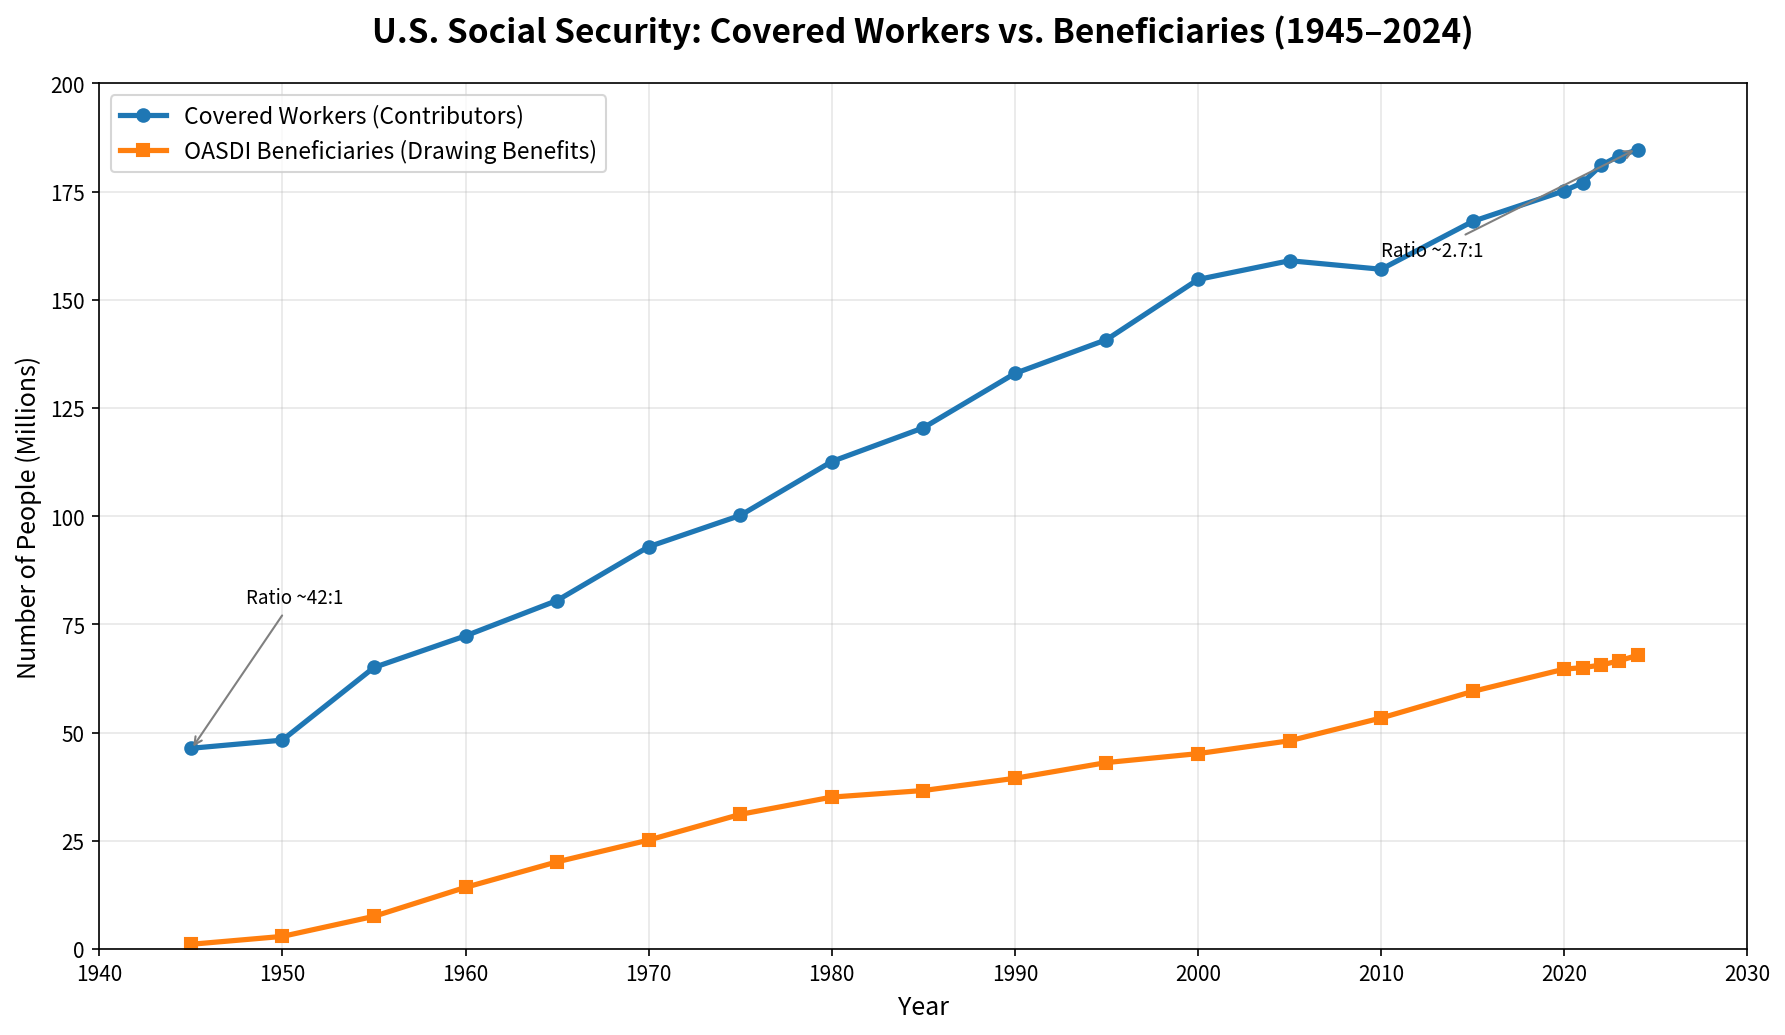
The chart doesn’t look bad unless you look at the ratio. In 1945 there were 42 workers for every individiual beneficiary. In 2024 that ratio was 2.7 to 1. The other factor? In 1945 an American aged 65, or “retirement age”, was expected to live about 13.5 years but today the life expectancy of a 65 year old is around 20 years. So we have a shrinking ratio of contributors to beneficiaries and at the same time the beneficiaries are living longer and therefore drawing even more.
Because this is Dissident Thoughts we of course need to address the race elephant in the room and it is a big one. The retiree population in America looks more like America of decades ago, that is to say very White. The Baby Boomers are around 71% White. My generation, Gen X, which is just about to start hitting Social Security age, is down to 59% White. Generation Z on the other hand, the young adults starting to backfill the workplace, is realistically speaking less than half White and of those Whites many are racially self-loathing as well as generationally bitter, whether for justifiable causes or not is another conversation for another day.
The point is that as the gibs start to run out, the once inviolable Social Security is going to start looking appetizing as a place for cuts. The rhetoric will go something like this:
“Why should young people of color be forced to subsidize the retirement of racist old White people?!”
Sure those “racist old White people” created the society these noble young people of color are living in but they would never admit that.
More broadly speaking, while America doesn’t spend nearly as much on “social spending” as Western European nations we do spend a lot in all sorts of places, from “education” to outright welfare to the prison system clogged disproportionately with non-Whites. The people who are replacing Whites in the work force are not only dumber and making less money relative to early generations, they are also far less capable of long term thinking. If the question becomes gibs now vs. security later, which do you think they will choose?
It might be difficult to swallow but America is just barely at the beginning of realizing the devastating impact of the Great Replacement. Right now the big hassles are non-Whites scamming the system and the inconvenience of going to Costco or malls full of monkey people jabbering in their monkey gibberish. That is going to get far worse in the near future as nons gain more political power thanks to the election of people like Abdul El-Sayed, who I am assuming “wins” the Michigan Senate seat in a few weeks, to Whites that despise White people like James Talarico who has a better than decent shot of winning his race for a Texas Senate seat. As the nons gain political power you can bet they will leverage that influence to the advantage of their own people at the expense of Whites.
Lest we get smug about the unfolding disaster in Western Europe and Canada, it is important to remember that they are just the sneak previews for what is coming to the U.S. It ought to also be a reminder of the old saying, failing to plan is planning to fail. The worst case scenario is coming and I am reasonably confident that most of our worst case scenarios are laughably optimistic.
Things look to get much worse and soon. Plan accordingly.
I’d love to think your readership knows better, but unfortunately I can guarantee you will get a number of the usual, predictable responses: “It’s not an entitlement program; it’s MY money!” “I worked hard all my life, and I want what I was promised!” “The government stole it!”
Yeah, yeah, every boomer and generation jones is super extra special and unique, and they aren’t representative of the stereotypical old Whites that everyone makes fun of. And besides, they deserve to live another 25 years relaxing and having others pay their bills – because “It’s MY money!” You can explain how Ponzi schemes work; you can tell them it was ruled a tax in 1937; you can show them how the average recipient gets far more than they ever paid in. None of it matters.
Let the games begin.